Written by:
Company law ‘still assumes we’re in the Victorian era’, says expert, as Baillie Gifford US Growth faces Saba vote
 Reading time: 11 minutes
Written by:
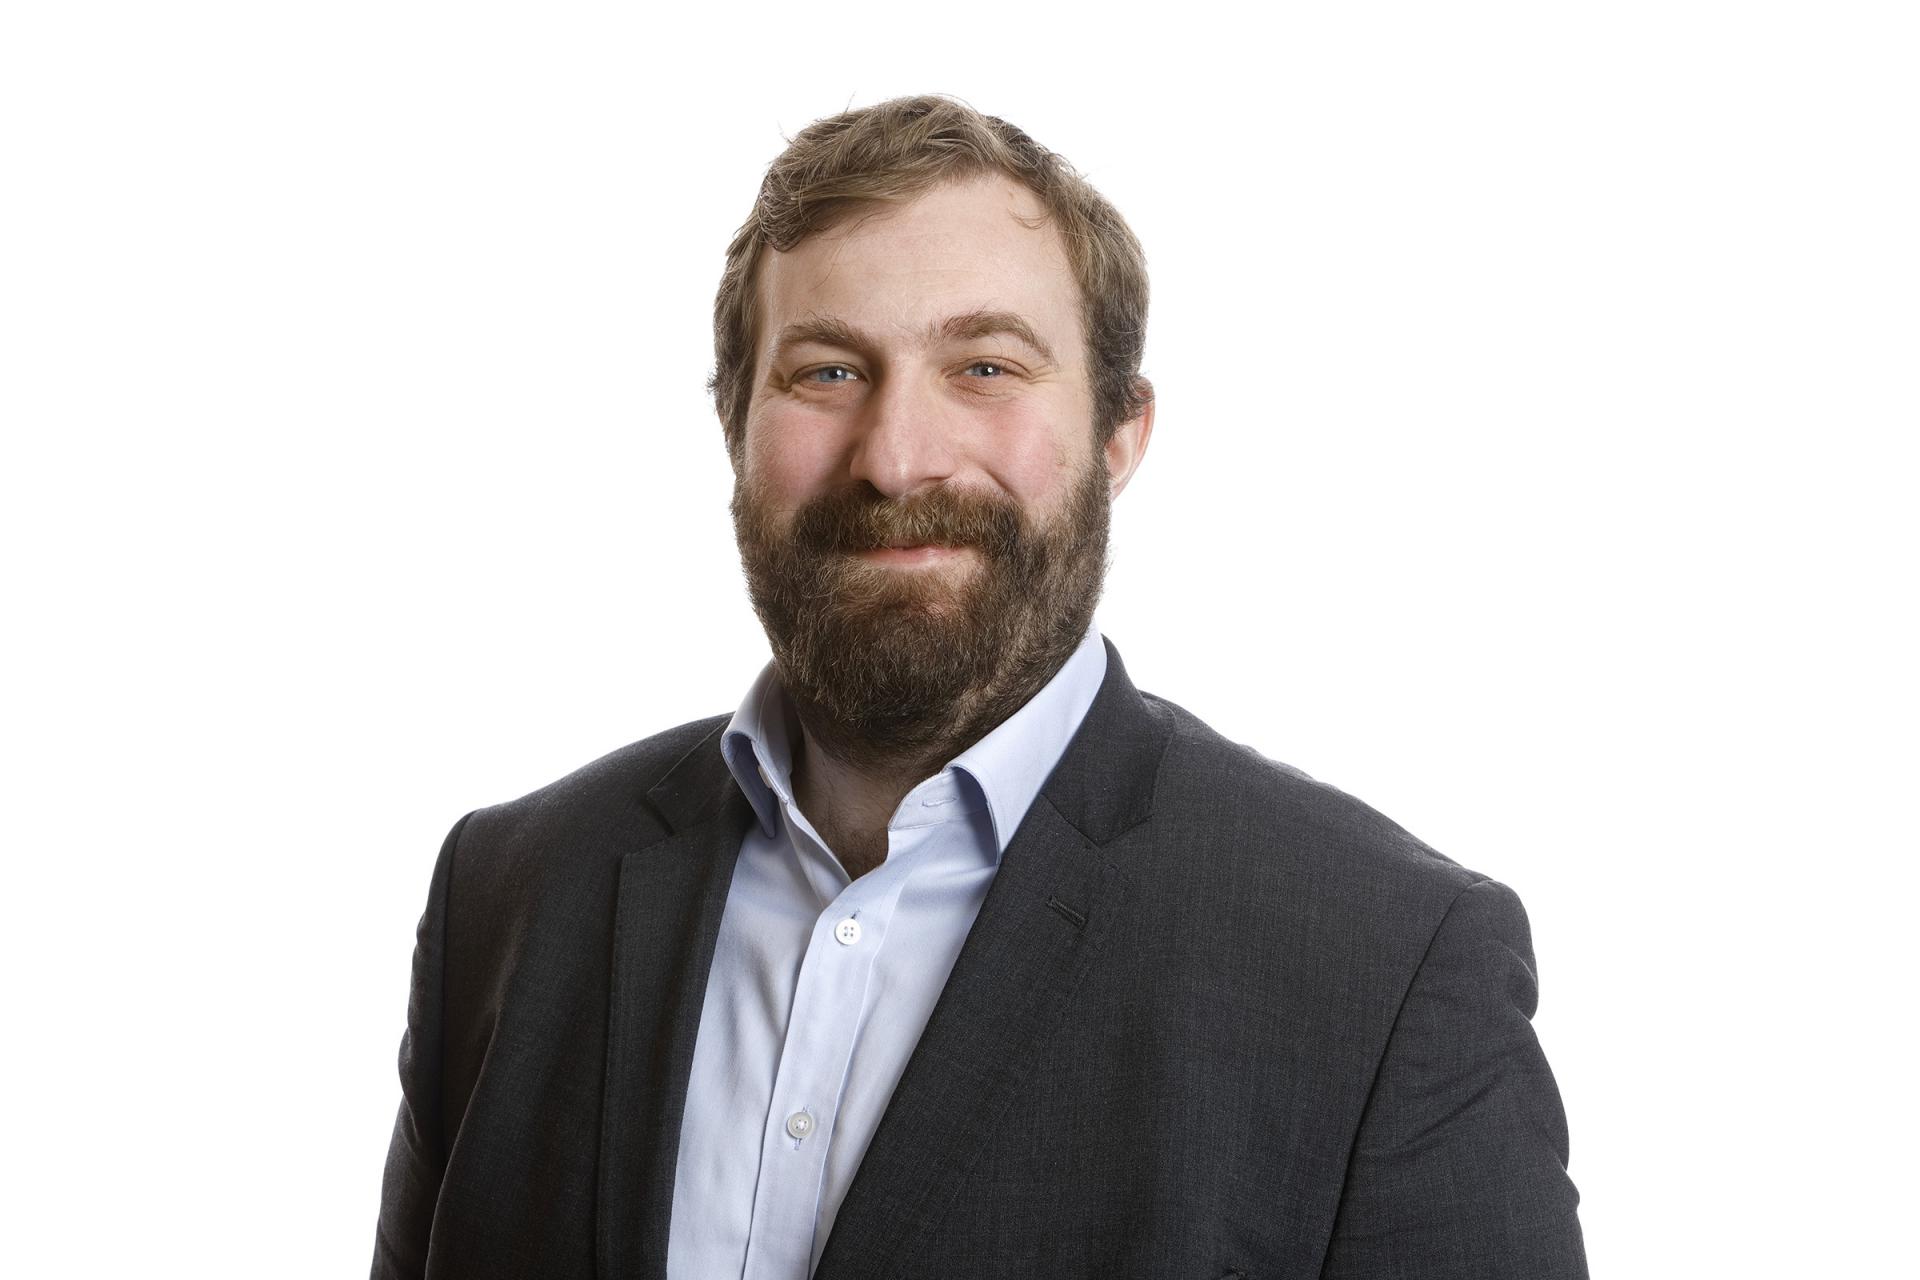
Dr Jonathan Hardman, a senior lecturer in company and commercial law at the University of Edinburgh
A legal expert has warned the Financial Conduct Authority’s (FCA) plans to update rules to stop companies using loopholes in regulation to take over investment trusts will fail to stop shareholders repeatedly requisitioning meetings.
The warning comes as Baillie Gifford US Growth Trust prepares to fight a requisition notice filed by Saba in August, calling for shareholders to appoint three Saba-nominated directors, Jason Chen, Thomas H McGlade and James Waterlow, to the board. The AGM will be held at the offices of Stephenson Harwood on 23 October.
The trust has issued a circular setting out what is at stake for shareholders if they fail to turn out to vote, allowing Saba’s requisition notice to pass and electing three individuals “linked with or employed by Saba” to the board, which it said would “severely compromise” the board’s independence.
During the financial year to 31 May 2026, the company’s share price and net asset value (NAV, after deducting borrowings at fair value) returned 44.5% and 31% respectively, exceeding the S&P 500 Index benchmark’s total return of 29.8%.
Chair Tom Burnet told Scottish Financial News that retail investors are the trust’s largest single shareholder block and their vote, regardless of stake, will decide the composition of the board after 23 October.
Burnet said: “If you’ve got a hundred shares, or a thousand, or a hundred thousand, it doesn’t matter. We need you out to vote. Otherwise I fear they’re going to get locked into something they don’t want, from a manager that isn’t going to be able to offer them anything like what Baillie Gifford is able to offer them.”
Dr Jonathan Hardman, a senior lecturer in company and commercial law at the University of Edinburgh, claimed the Companies Act 2006 needs to be rewritten instead of “patched,” arguing that the current approach has led to growing complexity in understanding the rules, which have not kept pace with the digital world.
The commercial law expert is set to publish an academic paper, titled ‘Saba Rattling in UK Investment Trusts: Three Lessons for Capital Market Regulation’, on the wave of investment trust meeting requisitions led by Saba Capital Management, after students on his Master’s course kept asking him questions about Saba’s activity in January 2025 during his corporate law classes. This was when Saba had requisitioned meetings at several investment trusts, including Baillie Gifford’s Edinburgh Worldwide Investment Trust, which it eventually won, due to a low voter turnout.
He said he “always kept an eye on the investment trust sector,” following previously working in the sector, adding that the multiple meeting requisitions represented “quite an interesting feat of corporate law” worth exploring in detail.
Dr Hardman told Scottish Financial News: “The rules… the operation of the rules in one isolated context isn’t always that interesting, but when it’s played out multiple times, it becomes quite an interesting thing,” explaining that the lag between drafting the paper and its publication had thrown up issues he hadn’t originally considered, such as that there is no cap or restriction on how often a shareholder can requisition a meeting so long as such requisition is not frivolous or vexatious.
He added: “It is possible for shareholders to repeatedly requisition such meetings. There’s no cap on it, there’s no restriction on when you can do it. And especially when you build a large stake, a large ostensibly minority stake, the risk of everyone else getting bored with what you’re trying to do makes your stake become more and more important. It’s one thing to whip up support from disinterested shareholders once, but to do it multiple times becomes a bit more of a challenging feature.
“You can keep asking the same question until you get the answer you want, if you have a large enough stake in the company to call the meeting.”
Dr Hardman’s paper identifies several regulatory questions raised by the Saba campaigns, including its most recent one against Baillie Gifford US Growth Trust, highlighting that one of the tensions is the strict director neutrality rule used in takeovers and the requirement for boards to issue recommendations on circulars.
“A shareholder can requisition a meeting to sack a director, and the directors have to say whether it’s the right thing to sack them or not,” he said. “Boards come back fighting quite strongly about notions to sack them, and that is likely to be genuinely what they believe best for the company… but it does jar a little bit to a lot of the neutrality positions that we force directors into other times where they could be conflicted.”
“A larger number of shareholders in investment trusts tend to be retail, who often hold the bulk of investment trust stock and receive information and voting rights through investment platforms. Different platforms did different things,” Dr Hardman said. “Sometimes it was the platform that voted without passing on information, sometimes major information would be passed on, sometimes no information passed on… There doesn’t seem to be many arguments for it to matter which platform you use, depending on whether you get pass-through voting or not.”
The expert pointed out that there is difficulty for disinterested shareholders to judge whether an activist investor is acting in good faith. “It’s quite hard, I think, given the institutional power that directors can throw against [an activist], to tell whether an activist investor trying to do the kind of thing that Saba is trying to do” is acting in good faith, he said.
“Should you be following them [the activist] or not… because boards are going to tell you no, and then… you kind of have to weigh up very strident statements from both sides about what’s going to happen. It’s quite hard to tell whether you should follow activist investors or not.”
He suggested a possible new duty requiring anyone requisitioning a meeting to act in the best interests of the company, similar to the duty already placed on directors generally. “Maybe an extra duty would make you feel comfortable that anyone trying to do this was doing it in the best interests of shareholders generally, rather than for a selfish reason,” Dr Hardman said.
He acknowledged the proposal would be difficult to enforce in practice, likening it to how rarely directors pursue claims against one another over breaches of duty. “It’s partially symbolic, because it’s hard to enforce, but it’s quite a powerful symbol, I would say,” he said.
Since the paper was written, its analysis has been overtaken by events, with the substance of Saba’s campaign, rather than just its mechanics, becoming the subject of an FCA consultation.
Under listing rules, investment trust boards must have a majority of independent directors, including an independent chair, with independence defined in relation to the investment manager. Dr Hardman said a gap emerges because Saba’s nominee directors are, at the point of appointment, independent of the incumbent manager – the entity they are trying to remove.
Dr Hardman has written separately about how vague the concept of independence is in UK law. “In the UK, we’ve got a bit of a vague notion. We don’t really define what independence is, it’s kind of one of those know-it-when-you-see-it style vibes, that’s a bit self-selected,” he said. “But what people have realised was there was a bit of a gap, so Saba are proposing to sack the boards and replace them with their own nominees.
“Saba’s appointees would be independent from the managers, because they’re the people they’re trying to sack,” he said. “And as soon as Saba were appointed as investment manager, they wouldn’t be independent, so they’d have to quit. But that process of appointment currently isn’t covered off in the independence provisions.”
The FCA’s consultation, which closed in August, looks to tighten the criteria for who can be appointed investment manager following a board shake-up. Dr Hardman said this could mean Saba “might fall foul” of new rules, but was doubtful it would close things off entirely.
“Because we’ve got such a fuzzy notion of independence, whatever you do, however you tighten it up, you can probably defeat the spirit of it whilst complying with the rules,” he said, warning that determined activists can “stage and sequence things” to work around new restrictions.
It is the repeated-requisition dynamic, rather than the independence gap already under consultation, that the legal expert said represents the bigger unaddressed risk and one regulators have shown no sign of examining. “That, I think, is a risk I hadn’t initially canvassed, that I think is one… we should tweak as well,” he said, noting that “nobody seems that interested” in regulating it and there are no live consultations on the point.
He said the key battleground for resolving these campaigns is not the courts or the regulator, but the shareholder vote itself. “The key fight has to take place on the shareholder vote stage,” he said. “Get the shareholders out, and get them to vote in the way that you’re hoping they will vote.” But he warned that voter apathy compounds the repeat-requisition risk, since retail investors with small stakes have little incentive to engage each time a new vote is called. “If I’ve got £100 worth of shares, why should I read 15 circulars in a 12-month period and bother to vote?”
Dr Hardman said this problem is rooted in outdated assumptions in company law. “Our legal architecture still assumes we’re in the Victorian era, where it was difficult to send in notices and requisitions,” he said. “Those thresholds that you’ve got now, and the percentages, they were quite hard to do once upon a time… now they’re very easy, especially with accumulated capital, as institutional investors keen to be activists.”
His paper points to the case of Middlefield Canadian Income, which moved to wind up following a second wave of requisitions, as evidence that Saba-style campaigns can succeed structurally even when individual votes are lost. “Investment trusts keep falling,” he said, citing the loss of the Saba requisition vote at an environmental impact trust in the summer, and describing the tone of Baillie Gifford US Growth’s circulars as “incredibly defensive,” reflecting the board’s attempt to bring the campaign “to a head.” He pointed to the trust’s circular, in which Baillie Gifford US Growth Trust said it had produced a plan to allow Saba to exit and that the plan was rebuffed.
Dr Hardman cautioned against assuming tighter rules are a simple fix. “The problem with regulating in this area is often that you risk at the same time under and over-regulating,” he said. “You can under-regulate by still leaving loopholes for people to do what you don’t want them to do, and over-regulate by stopping people who do what you want them to do from doing that as well.”
He illustrated this with a hypothetical: an activist who proposes a replacement plan when ousting a board is open to attack over that plan, while one who proposes no plan is open to attack for having none. “If you take the Saba bit out and replace it with a hypothetical party, they either come in with a plan, in which case they’re open to attack for that plan, or they don’t have a plan, in which case they’re open to attack for not having a plan,” he said. “It’s a catch-22.”
He also questioned whether the FCA’s securities-law fix could ever be sufficient on its own, given that company law, separate from listing rules, sits underneath the same problems.
He noted the Companies Act 2006 is 20 years old this year, in what has historically been a roughly 20-year cycle of major legal restatements, and argued that any FCA-level changes “need to be backed up by at least a re-examination of these fundamental basic rules” in Westminster.
He pointed to the piecemeal way the Act has been amended, with 65 new sections inserted between the original Section 790 and 791 alone, as an example of the complexity that results from patching rules rather than rewriting them.
Dr Hardman said regulating the Saba-style playbook without knowing whether individual activists are acting in good faith is inherently difficult, adding: “It’s pretty obvious that Saba want to appoint themselves as investment managers.” He argued that removing that ambiguity does not resolve the underlying policy question of how to distinguish genuine reform attempts from self-interested takeovers, a question he said applies “to any active proposal,” not just to Saba.

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE