FCA urges crypto firms to prepare for regulation in October 2027 as crypto investors face no FSCS safety net
 Reading time: 8 minutes
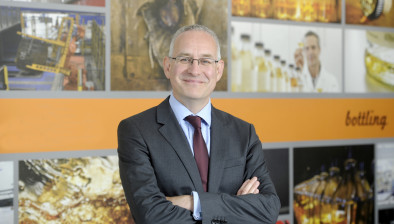
Val Smith, FCA’s head of authorisations, payments and digital assets
The Financial Conduct Authority (FCA) has urged firms to prepare for the UK’s new regulatory regime, warning that crypto-investors will not have access to the Financial Services Compensation Scheme (FSCS) for their digital asset investments.
Val Smith, the FCA’s head of authorisations, payments and digital assets, told Scottish Financial News that the new framework would bring a wider range of cryptoasset activities within the Financial Services and Markets Act (FSMA), requiring firms to demonstrate that they have the governance, controls and risk management arrangements needed to meet regulatory standards.
The regime is due to take effect on 25 October 2027. It will bring new activities within the FCA’s remit, including the issuance of sterling-backed stablecoins, which will be subject to requirements around the resilience of issuers and the assets backing their coins.
Smith said stablecoins could improve the efficiency of payments and wholesale market activity, potentially reducing the cost of cross-border transactions. However, the extent of those benefits will depend on how firms develop and use the technology.
The new regime will not extend Financial Services Compensation Scheme protection to cover cryptocurrency. However, eligible consumers will still be able to refer complaints to the Financial Ombudsman Service, providing a separate route to redress in applicable cases.
Wallet security also presents risks for consumers, particularly where access to cryptoassets depends on private keys. If a key is lost, recovering the assets may not be possible, depending on how the wallet is structured and whether a provider offers recovery support.
Smith said the FCA would examine how firms manage these risks, support customers and maintain access to their cryptoassets. “When firms come to us to be regulated, we will look at how they manage the risks, how they support their customers and how they ensure access to their services, products and cryptoassets,” she said.
She added that firms must clearly explain how their services work and what happens if something goes wrong. “There is a certain amount of responsibility that consumers take on in all financial services. There needs to be clarity from the institution offering the service about what happens if something goes wrong,” Smith said.
Firms will also be expected to comply with the FCA’s Consumer Duty, which requires them to focus on delivering good outcomes for customers, including how they support customers when problems arise.
“This regime does not include access to the Financial Services Compensation Scheme. It does include access to the Financial Ombudsman Service, so some of the safety nets are there,” Smith said.
Sterling-backed stablecoins enter FCA remit
The new regime will broaden the range of cryptoasset activities subject to financial services regulation. Firms currently carrying out cryptoasset custody or exchange activities in the UK must register under the Money Laundering Regulations, while the new framework will bring qualifying cryptoasset activities within FSMA.
The legislation provides for nine new regulated activities, which Smith said broadly fall into six business models, including arranging and dealing in cryptoassets and issuing UK sterling-backed stablecoins.
“For the first time, sterling-backed stablecoins will come within our remit. We’re already starting to see some positive developments in the market,” she said.
Smith said the FCA was seeing growing interest in how stablecoins could be used in wholesale markets and payments, with firms exploring their potential to improve transparency, speed and efficiency.
“There’s conversation in the wholesale markets about how stablecoins might be used to create greater stability, while offering some of the additional features we see in digital assets, such as transparency, speed and efficiency,” she said.
The technology could also help streamline payments and improve services for customers, she added. “We’re also starting to see people thinking about how they might use stablecoins in payments to make transactions more efficient and provide a better service to their customers.”
Under the new framework, issuers of UK sterling-denominated stablecoins will be required to back their coins with assets, with the FCA examining the resilience of the issuing business and the arrangements underpinning the stablecoin.
Smith said the assets backing a stablecoin were central to maintaining confidence in its value, pointing to problems experienced by some international stablecoins where the backing had not been sufficiently resilient.
“There is potential for stablecoins to reduce some of the costs involved in settlement and payments, particularly cross-border payments,” she said.
“Depending on how people choose to set things up, they might reduce those costs or perhaps eliminate them. That’s one of the areas we’re interested to see the market develop.”
Tokenisation creates further opportunities
Beyond cryptoasset trading and stablecoin issuance, Smith said the FCA was also examining the potential of tokenisation, which uses digital tokens to represent assets or rights.
Although tokenisation falls under a different part of the regulatory framework, she said it remained within the FCA’s broader remit. The technology could offer benefits including greater transparency, faster processing and improved efficiency.
“There is great potential in digitisation and tokenisation. Tokenisation sits under a slightly different part of regulation, but it is still within our scope,” she said.
The regulator has used sandboxes and innovation pathways to explore potential applications, with firms helping the FCA understand how the technology might work before the rules were finalised.
Smith said the FCA would continue to learn from firms as they applied for authorisation and developed new business models. The regulator also works with the Bank of England through the Digital Securities Sandbox, which allows participants to explore the use of digital securities.
However, she declined to comment on individual firms participating in its initiatives.
“The opportunity is to use this technology right across financial services and encourage people to think about it differently,” she said. “Previously, thinking about cryptoassets has been relatively contained. This is now opening up across financial services.”
FCA urges firms to prepare for authorisation
With the regime approaching, Smith said firms should start by understanding which activities they intend to carry out and how those activities fit within the new rules.
She said businesses needed to consider their products and services, the customers they wanted to serve and whether their organisational structures and staff had the skills and capabilities to operate within the regulated market.
“The starting point for any business is: what does my business look like? Who am I doing business with? What products and services do I want to offer in the market? Then you need to consider how those fit with our regulations,” she said.
Smith said the FCA wanted to see applications from firms that had properly considered their business models, rather than those applying simply to find out whether they needed authorisation.
“I’m looking for firms that have thought about their business and put together a clear account of its purpose, how they intend to make money, the people they will work with and who will be accountable and responsible,” she said.
That preparation should include understanding the risks associated with the business and establishing appropriate controls to manage them.
Smith said firms should also plan for the time needed to introduce new systems, strengthen risk management arrangements, establish supplier agreements and secure banking relationships.
“I don’t expect everybody to have done everything already, because businesses need to use their capital efficiently,” she said. “But do you have a plan that means, come October, you can confidently say to me: ‘I’ll be ready to meet the standards’?”
The FCA is encouraging firms planning to seek authorisation to speak to the regulator before submitting an application, allowing them to discuss how their business models fit within the new framework and identify areas that may require further work.
Financial crime and resilience under scrutiny
Financial crime controls will be another key consideration for firms seeking authorisation, with Smith saying cryptoasset businesses would be expected to demonstrate how they manage fraud, money laundering, sanctions and terrorist financing risks.
She said firms needed to understand their customers, assess the risks associated with their transactions and have systems capable of identifying unusual activity. “For any financial services firm, we would expect strong financial crime controls covering fraud, money laundering, sanctions risk and terrorist financing,” she said.
The FCA would also expect firms to consider how their businesses might be affected by market volatility, operational disruption and problems with suppliers.
Smith said the global nature of cryptoasset markets created particular challenges, making it important for firms to identify potential threats to their resilience and establish plans for responding to different scenarios.
The new regime will introduce prudential requirements for the sector, including requirements to hold regulatory capital, providing a financial buffer if a firm’s resilience comes under pressure.
“There are risks in this market, as there are in any other part of the market we regulate. Firms need to understand those risks and put the right controls in place to manage them,” she said.
Smith added that the FCA had worked extensively with the industry during the development of the regime, publishing discussion papers and 10 consultation papers and holding more than 40 events during the year.
She said engagement with firms would remain important as the regulator assessed new business models and considered how the rules worked in practice.

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE