Written by:
Private equity ‘middle of the market’ faces increasing pressure, warns Columbia Threadneedle’s Andrew Carnwath
 Reading time: 9 minutes
Written by:
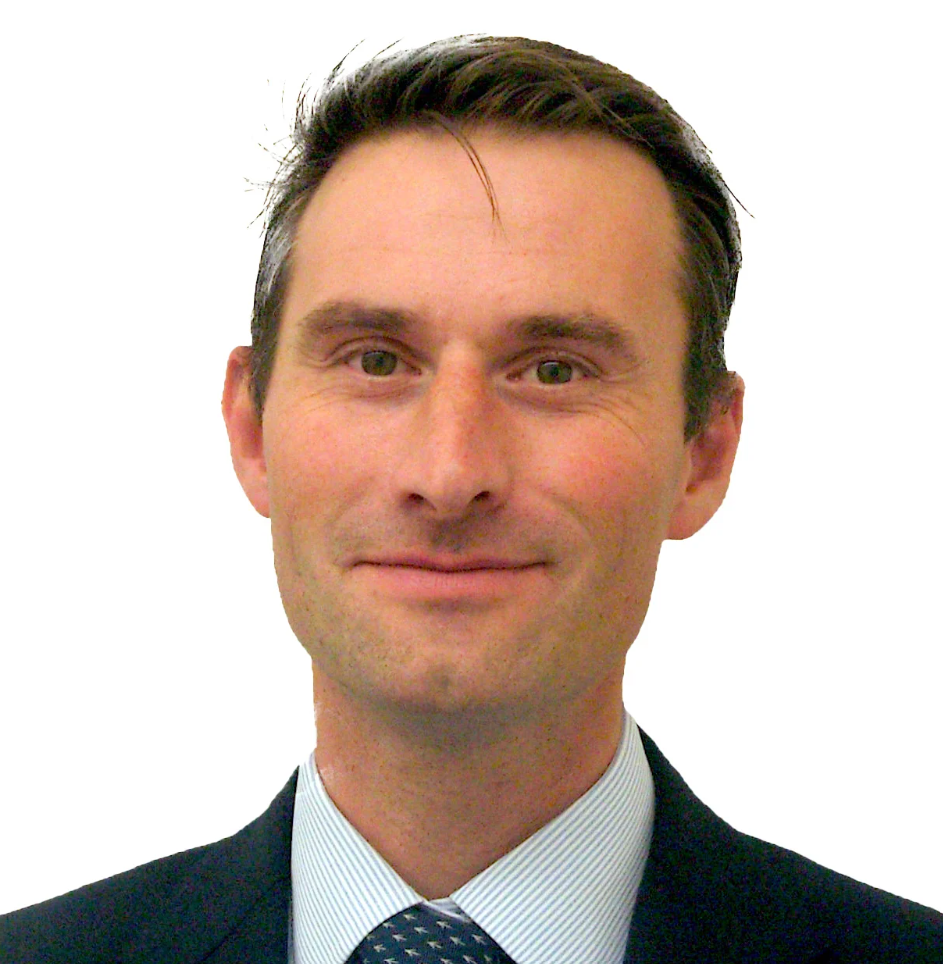
Andrew Carnworth of Colombia Threadneedle Investments
Columbia Threadneedle Investments’ Andrew Carnwath has warned that private equity is splitting in two, and that managers caught in between are coming under pressure.
The firm’s head of private equity was speaking about the future of private markets at the Investment Association’s Scotland Conference on 5 November. The panel explored the role of private capital in financing growth, evolving investor demand, and how the regulatory and economic environment is shaping the market.
He was joined by Kate Baker, global head of alternatives capability at HSBC Asset Management, Bremner Garner, vice president of product development and strategy at Brookfield Asset Management, and Michael Cummins, solutions architect at Fundguard. The panel was moderated by Namita Kain, head of private markets at the Investment Association.
Carnwath said private equity will keep growing rapidly, he argued: “I think we’ll continue to see very rapid growth and that’s driven by very strong returns but also diversification, and the fact that private equity can provide investors with access to business models and high-growth sub-sectors that are just very difficult or sometimes impossible to access through public markets.
“I think the industry is somewhat changing and bifurcating. On one side we’re getting larger and larger managers that can provide huge scale and consistent, if lower, returns. And then on the other side you’ve got smaller specialist managers providing real alpha. And I think the middle of the market is going to come under increasing pressure, and you’re going to get the very big scale or very specialist.”
He described two types of secondary. The more conventional, LP secondaries, is “where an investor is selling their holding partway through”. “Historically, that was seen as a sign of weakness and it sort of forced sales,” he added. “That’s increasingly being used by people as a portfolio management tool, and I think that just shows the maturity of the industry.”
Of GP-led continuation funds, where “a manager raises a new vehicle to acquire one of the portfolio companies that they manage”, he said: “That’s not without its sceptics. But I think overall it’s a positive for the industry. It provides options for investors, and as long as investors are really able to look at the opportunity, take a view on it, and ensure that conflicts have been managed, I think it’s great to provide options.”
Concerns over capital concentration
“We’re seeing more and more capital flowing to larger and larger funds, managed by larger and larger managers, and I don’t think that’s healthy for the private equity industry,” Carnworth, continued: “Very large funds are investing in more competitive, more transparent markets, they said, which “drive down the returns and therefore investors are disappointed”.
He said noted that these companies already have access to finance, so “I don’t think it will drive the acceleration of the economy.” Instead: “When you look at the lifeblood of the UK economy, it’s the SME. There are thousands of SMEs in the UK where they’re established, they’re profitable and they’re growing quickly, and through investment, private capital can help accelerate them.
“They can internationalise, they could provide high-quality jobs within the UK and drive the economy forward, whilst also providing great risk-adjusted returns for investors.
“I think it takes people to be innovative. I think it takes people to not follow the herd and invest in the brand name.” He added the lower mid-market, where their firm specialises, is “underserved in terms of capital”.
They also rejected the idea that founders taking money out in a buyout is less valuable than money going into a company. “You need to incentivise founders to create value. Take some money off the table, they can then take more risk, push harder, grow faster, but also stimulate the next wave of companies.”
On Mansion House, he said: “I’m really supportive of these policies which are trying to put money to work in private markets. If it’s done well, that has the potential to boost the economic growth we all want to see and then, secondly, provide access to areas like private equity which are restricted to sophisticated investors. But I think we need to stick with the basics: to drive better returns for the investor.”
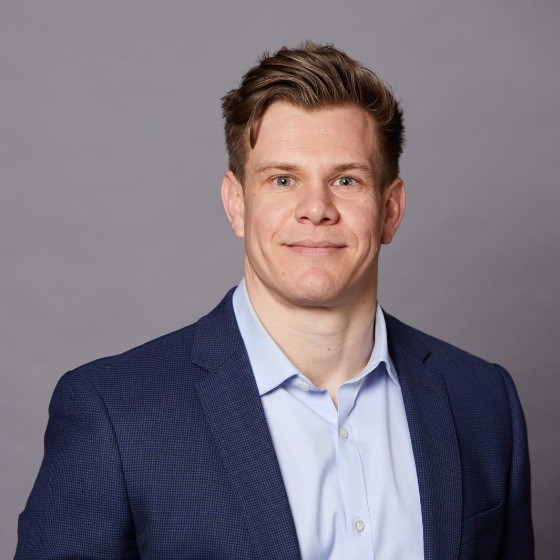
Bremner Garner
The UK’s retail gap
Garner said the biggest opportunity lies with individual investors. “Institutions have for a long time now been investing in private markets, whereas individual investors have not. That’s going to change,” he said, through defined contribution pensions, IFAs and direct access.
“That gap is the opportunity. The average private markets allocation for an individual investor in America is six to eight per cent. We’re at 0.1. So we are so far behind the curve.” Part of the hesitancy, he said, is “a little bit of scar tissue from Woodford”, which education, new structures and the market itself should help to ease.
Baker said portfolio construction is critical. “You really want to start with the outcome. What are you trying to achieve by making a particular allocation? Is it long-term growth? Is it exposure to assets you can’t get on the public market? And then you need to think about how your allocation to private assets is going to fit in your portfolio: how will it play alongside your existing public market exposure, your cash, your liquidity requirements.”
She said private markets have “a very important role in that portfolio, but it needs to be within that”, and that education must evolve “so that they’re focusing on the role that each asset is playing”.
Liquidity and product design
Baker added that product liquidity terms must be “clear and suitable for the underlying assets”, and that the investor must “understand what they own”. “How long can an investor have that money tied up for? Different investor types, defined contribution members, high-net-worth clients, are all going to have different needs, so we need different access routes and different solutions for them.”
She warned that “the dealing date does not guarantee liquidity”, and said investors need to understand notice periods and redemption terms “if a lot of people want to redeem”. After investing, clients need “clear reporting that they can understand”.
Garner said: “Interval funds in the US guarantee 5% liquidity per quarter. ELTIFs in Europe, you have to have a strict percentage of liquid assets. And then LTAFs have got things like a 90-day notice period, to allow time for the investment managers to get some liquidity.” Education is still needed, they said, because “it doesn’t mean you’re guaranteed all of your money back”, and some US investors had not thought that through.
On regulation, Carnworth said: “There’s been huge steps forward. There are still some to go.” The long-term asset fund “works very well in the DC market, less well in wealth markets”. Because it is a non-standardised asset, “you can only have 10” in it, and “maybe that could be lower”.
Operations before regulation
Kain drew on the Investment Association’s modernisation report, published a few weeks ago. One said its big conclusion was that “operational infrastructure is key to broadening access way more than the regulation”.
She said the report had three key messages: more work on demand and education in the wider advice market, operational barriers being “most important now, more than regulatory or structural barriers”, and education across the value chain. “If we’re going to do this expansion in a responsible manner, we’re going to be judged on the access being appropriate and the investors understanding those products, not just on whether we increase sales.”
On technology, Cummins said: “A lot of it comes down to the unstructured nature of the deal complexity, which becomes quite difficult to operationalise. Historically the problem was solved by standardising the data and then building technology on top of that standardisation. It’s going to be interesting now to see if you can take the unstructured work that humans are doing right now and then build the technology on top.” They added: “There’s a huge opportunity in the technology sector.”
Scotland and Europe
Asked where Scotland has a competitive advantage, Carnworth said: “A lot of it is around power. Renewable energy, the ports.” Much of this is already happening, they said, and the bit to work on is getting managers to base themselves here.
Baker said their direct credit approach considers “not just Scottish headquartered businesses, but also businesses which have material operations across Scotland, and we think that’s a really unique opportunity”.
Garner, said: “There’s no one-size-fits-all on an asset class.” Carnworth said: “As a European, I think it’s quite nice to see at the moment we are seeing more of a focus on Europe. A lot of asset owners are suddenly feeling a little bit overweight to the US in terms of private equity and looking elsewhere.”
In the lower mid-market, he said: “There’s that fragmentation, that complexity in Europe, with all the different languages, the legislation, the different cultures, all of which makes quite an inefficient market and therefore the potential to get an edge.”
What next?
Asked for one development that could surprise investors and policymakers, Carnworth chose the “growth of impact” he explained: “I mean investing in companies that are addressing fundamental human or planetary needs, whether that’s curing cancer or tackling climate change. And I think that will grow rapidly, against the kind of headlines that you see in the ESG space.”
Another predicted that in five years “you’ll have daily valuations, you’ll be able to trade easier”, and “it would be part of your pension defaults, whether you like it or not”.
Cummings said the conversation creates “so much nervousness in the back office”, but that operational infrastructure is the key, claiming: “Technology will save us all.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE