Written by:
Equilibrium’s Sam Patterson on the blind spot in financial planning
 Reading time: 5 minutes
Written by:
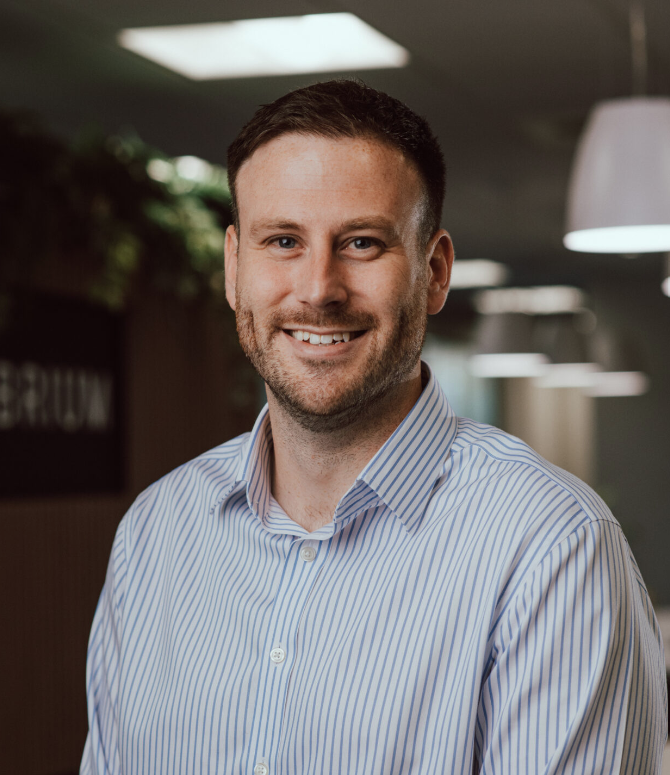
Sam Patterson, head of proposition at Equilibrium
Financial planners have the knowledge to help clients understand their goals and protect their interests.
“Rightly or wrongly,” most clients are high-net-worth individuals who are retired and have more time to think about what they want to save or how to use their assets.
Last year, it was reported that nearly half of UK households with a net worth of more than £500,000 managed their finances without professional advice.
Sam Patterson, head of proposition at Equilibrium, claimed many advisers followed a process that didn’t consider cash or student loans.
Mr Patterson has been giving presentations to financial planning professionals on student loan debt, prompted by his own case: £42,000 borrowed, £10,500 repaid, and a balance now 20% higher than when he started.
He claimed the reaction in the room is the same every time: disbelief that a topic this basic remained unaddressed by an entire profession, arguing it is not a “lack of knowledge” but a process built around their typical client, high-net-worth individuals.
The expert said: “For financial planning professionals, the real issue is process rather than knowledge.
“The first step is working out how much cash a person should have, and every firm and adviser will have different numbers. At Equilibrium, the approach is conservative, running about a year’s worth of expenditure in cash. Establishing how much cash someone should have, and why, limits the amount held unnecessarily, since it’s well documented that many people in the UK hold levels of savings in cash well beyond what a sound financial plan would suggest.
“Once that’s established, the interest rate being earned can be assessed, and depending on how much cash is involved, it can be spread across different banks.”
However, people are only protected up to £120,000 per banking licence, not per individual bank, meaning interest earned over time can unknowingly push savers past that threshold.
From April 2027, the annual Cash ISA allowance drops to £12,000 for under-65s, and tax on savings interest outside ISAs increases by 2%, following decisions made in the Autumn Budget last year by then Chancellor Rachel Reeves.
As a result, more people are expected to register as self-employed to pay off this additional tax from the savings generated.
“If you’re employed, you’re used to paying tax through PAYE, so you don’t really have to do it yourself. Money arrives in your bank account, and you know you’ve paid your tax; your employer’s tax code takes care of that. But if you have interest, you’ve got to do it by self-assessment. If you’ve ever done a self-assessment tax return, it’s a bit of a pain”, he said.
“There are lots of online gateways, you have to set up a government gateway, you have to go through tens of different pages asking things you don’t properly understand. If you do have a tax liability on savings interest, even if you’re aware of it, it’s not a nice experience to have to do.”
Mr Patterson conceded: “This profession deals mainly with high-net-worth clients, there’s no getting away from that, that’s who the profession serves in the main, rightly or wrongly.
“That’s where starting to talk about student loans, starting to think about cash, is still needed in this profession. It’s applying the same discipline to cash that’s common practice in investment management.”
The adviser admitted that the key approach he tells clients is to “not get carried away in speculation” ahead of the Budget following more than a decade in the profession, noting that speculation intensifies in the six to eight weeks before it happens.
“There’s been speculation for probably the past five years that tax-free cash in pensions might be taken away or reduced, so people rush to crystallise pensions and take tax-free cash out if they can, and then it doesn’t happen,” he said.
Analysis of FCA data by AJ Bell revealed that excess tax-free cash withdrawals of around £10 billion were triggered by speculation around the 2024 Budget, illustrating the scale of the impact on retirement plans and the wider economy.
“One thing that can be guaranteed is that there will be a change, but that change might itself change in a following budget, pensions and investments and tax will always change. The advice is always to make decisions on what you know, not on what’s being speculated, because you don’t know where those speculations in the media and press come from.
“What’s wanted from a financial planning professional, from an expert, is decisions made on what they know, not on what they’re reading in the papers.
“It’s a good example of hearing something and having a brain that says action is needed, when it might or might not be, so it comes back to looking at the process, what is known, and planning accordingly. That’s actually the whole point of a financial planner, and it’s an area where the profession needs to become more accessible.”
Mr Patterson revealed he has sat more exams in the profession than he sat in school and university combined, ensuring his knowledge is up to date with all the latest regulatory changes.
“The profession as a whole needs to be more widely known, and there should be a basic level of financial education in schools, covering different asset classes and how they work, since it’s rare now for a client to even mention gold, for example.
“Different people want different things: someone who doesn’t mind ups and downs and isn’t reliant on the money over a long time horizon might find gold appealing, there are many ways to look at it.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE