Written by:
SME lending nearly halves as share of UK GDP, Allica Bank finds
 Reading time: 5 minutes
Written by:
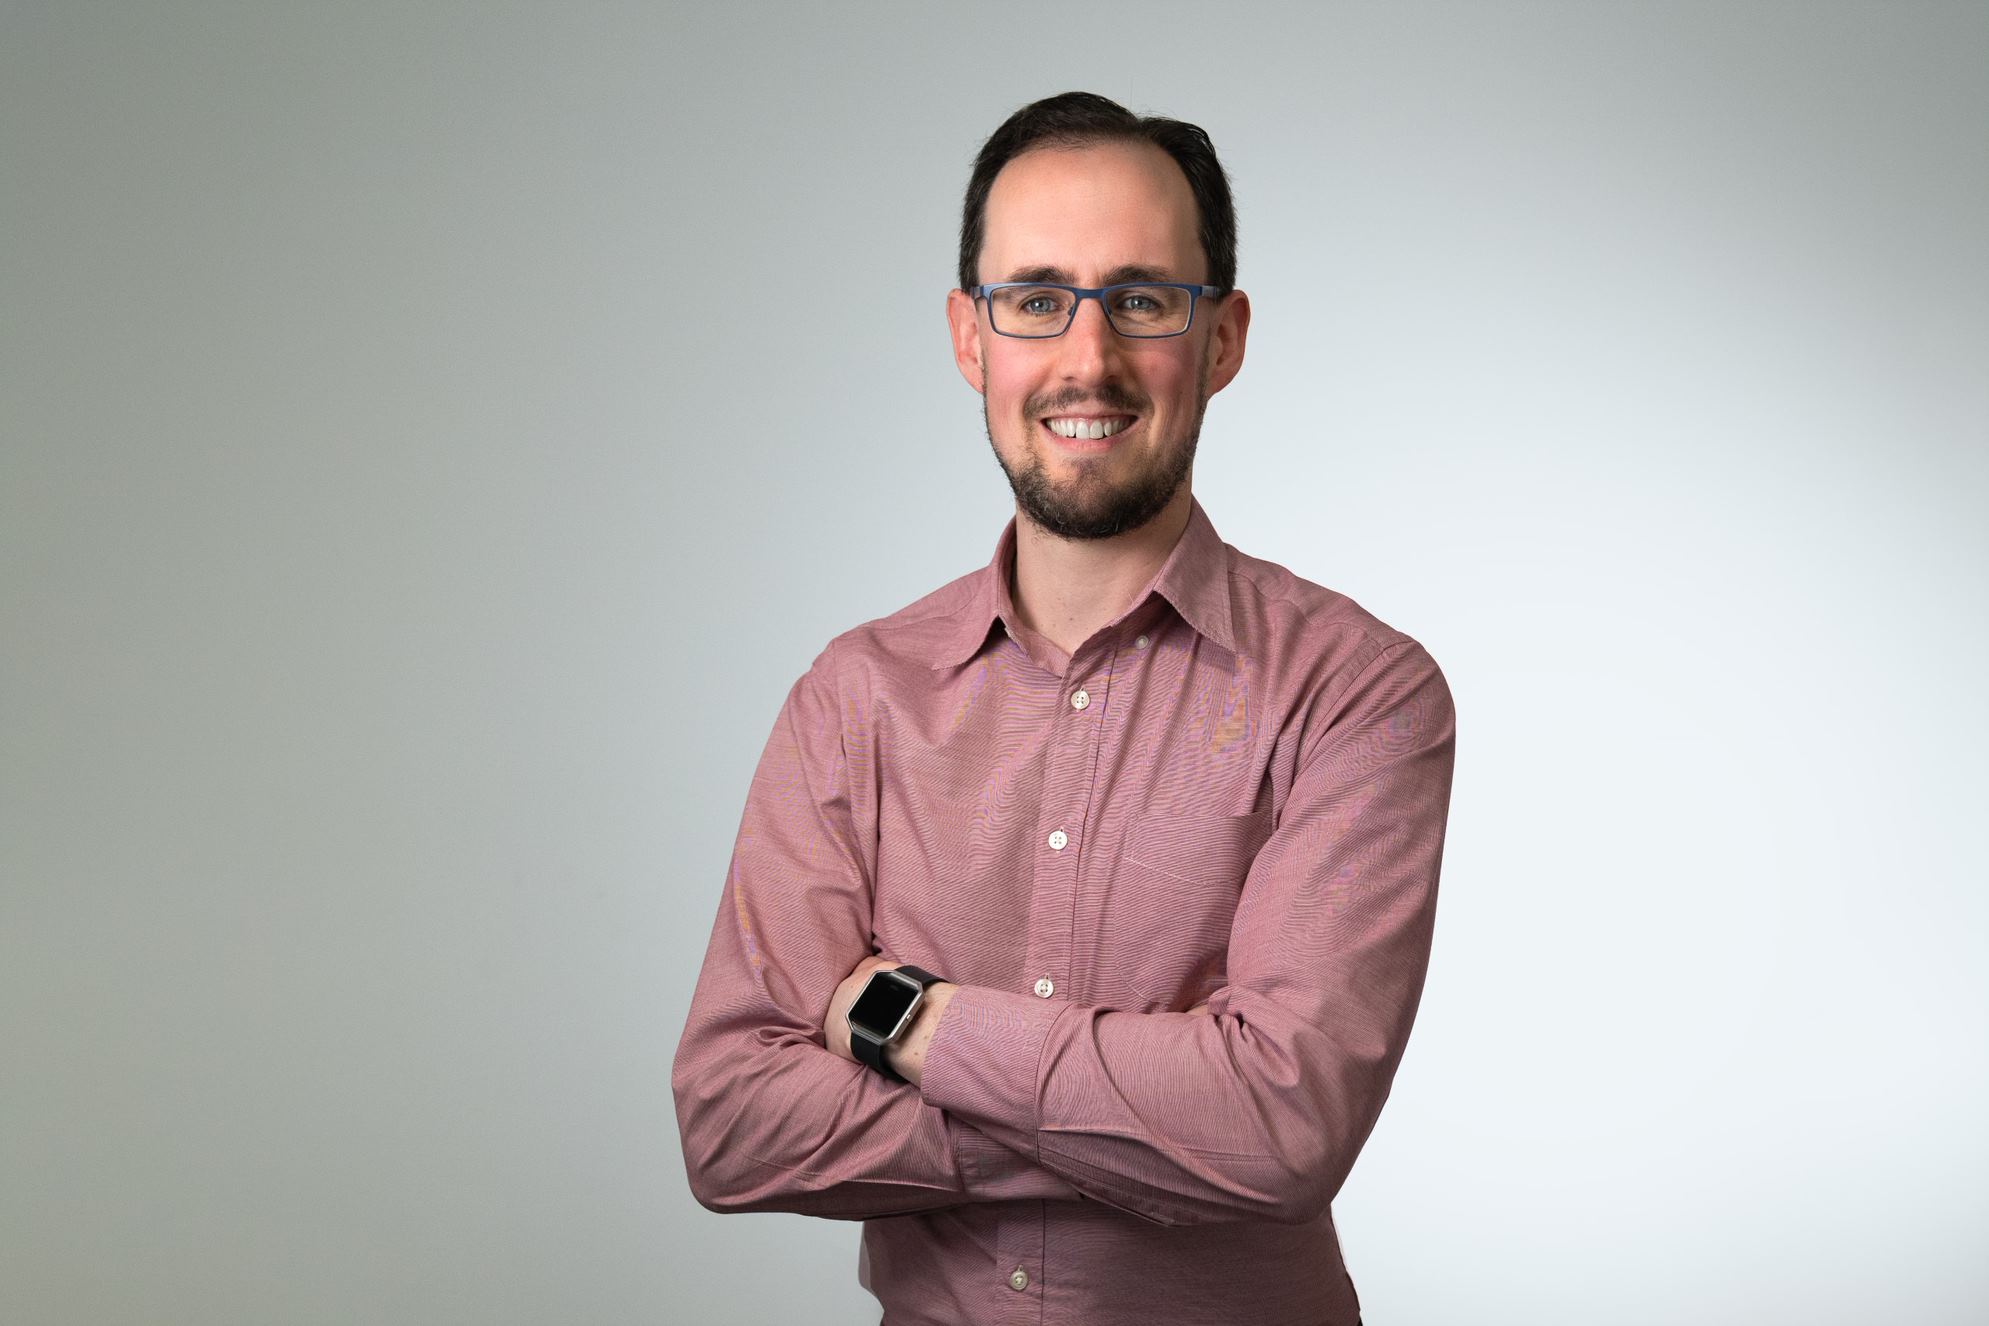
Richard Davies, chief executive at Allica Bank
Lending to small and medium sized enterprises (SMEs) has almost halved as a proportion of Gross Domestic Product (GDP) since 2011, new research from Allica Bank has revealed.
The challenger fintech revealed that the UK’s 592,500 established SMEs employ around 10.7m people and generate 37% of private sector turnover. The report estimates there are 16,300 established SMEs, businesses older than 10 years old, in the UK that grew turnover by over 20% in the past year and can make a meaningful contribution to future growth.
Allica Bank found that SME lending as a proportion of GDP almost halved, from 12% to 6.5%, with bank lending to SMEs increasingly dominated by real estate activities, which make up half of all lending to SMEs despite being only 3% of the SME population since 2011.
It said: “Allica’s previous research suggests the SME lending market is characterised by a negative structural equilibrium, contributing to the UK’s investment rate being the lowest in the G7. We estimate that UK SMEs face a £65 billion lending gap on a stock basis and a gap of around £15 to £20bn on an annual new lending basis, with the gap particularly concentrated in the provision of productive credit; finance that supports business investment, expansion and working capital needs.
“Over the last few decades, bank lending in the UK has been increasingly biased towards residential mortgages, with bank lending to businesses well below the historic trend over the last 15 years. This is driven by a pronounced bias towards collateralised lending, especially property-backed loans, alongside a corresponding decline in unsecured or cashflow-based lending that supports business investment.”
The bank claimed lending decisions are now shaped by “risk-weights and capital requirements, which favour low risk, secured exposures. This has resulted in a misalignment between the structure of bank lending and the needs of the modern UK economy, which is now predominantly service-based and therefore less collateralised.”
It also found that loan margins on SME lending have declined relative to the 1990s, despite significantly higher capital requirements, highlighting banks prioritising low-risk and highly secured lending with “reduced appetite for higher margin” and “higher-risk productive credit”, explaining that credit supply has become “increasingly conservative”, with less financing available for innovation and growth.
It added: “The long-term contraction in productive credit supply has been accompanied by a structural decline in SME demand for finance, driven in part by a decline in SMEs’ appetite to borrow. SME application rates for finance have fallen significantly from 65% in the late 1980s to 24% in the period 2023-2025, while loan rejection rates have increased from 5-10% historically to around 36% today.”
The research found that 77% of SMEs report a preference to grow more slowly rather than borrow for faster growth. It found that the decline in provision of credit to SMEs is most pronounced in the construction sector.
Overdrafts accounted for 31% of SME lending in the late 1990s, but now represent only around 5%. Allica Bank claimed the decline has had a “direct impact on SMEs’ ability to manage cash flow and finance day-to-day operations, particularly during growth phases when working capital requirements increase.”
The research, based on the Office for National Statistics’ latest UK business counts data, suggested that established SME numbers are disproportionately declining in the areas where they support the greatest share of jobs.
In the most rural local authority districts in the UK, established SMEs have declined by 2.3% in the past three years, compared with 1.2% growth in the most urban areas. These urban districts are three times more likely than rural districts to have experienced recent established SME growth. Between 2016 and 2026, established SME numbers increased by just under 7% across the UK, with London accounting for 44% of net growth.
It found that rural areas rely heavily on established SMEs for employment, supporting 48% of jobs on average compared with just 33% in the most urban areas. The East Midlands, South West, Wales and Scotland all recorded growth of around 2% over the ten-year period for jobs, compared to London’s 19.1% growth over the same period, according to the research.
The report identifies certain local authorities that have experienced the sharpest decline in established SME numbers in the past three years, such as Moray in Scotland at -4.9%, North Ayrshire at -4.8%, North Lanarkshire at -3.7%, East Ayrshire at -3.1% and West Dunbartonshire at -3.0%.
It comes as Prime Minister Andy Burnham has pledged to deliver “good growth in every postcode” and Allica Bank claimed that pledge cannot be met without established SMEs as it called on the government to take four steps:
• A Scale-up Guarantee: Create a new tier of the Growth Guarantee Scheme offering a 70% guarantee on facilities between £2 million and £5 million for high-growth firms that lack tangible assets.
• Support regional skills development: Fully devolve adult skills funding to Strategic Authorities and introduce a Growth & Skills Levy pool, with a focus on developing established SME AI skills.
• Reform business owner taxes: Reduce the cost of doing business for established SMEs and introduce an established SME Reinvestment Relief to encourage business reinvestment.
• Establish regional established SME Growth Forums: Give established SMEs a permanent voice with local leaders to identify barriers to growth and shape Local Growth Plans.
Richard Davies, chief executive at Allica Bank, said: “The Prime Minister has pledged to deliver ‘good growth in every postcode’, and established businesses can make it happen. These firms are the engine of regional growth across the UK. They keep local economies running and communities thriving.
“They may not be the hyper-growth scale-ups that grab the headlines, but they sustain local jobs for decades, often in the very places national growth strategies overlook. We urge the Government to put established businesses at the heart of its growth agenda and its mission to deliver good growth in every postcode.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE