Written by:
Baillie Gifford’s China bet is becoming a wager on AI, not a broad recovery
 Reading time: 4 minutes
Written by:
Managers reported a 'two-speed economy' in China
Baillie Gifford China Growth Trust outperformed its benchmark in the first half of the year, despite falling in absolute terms, as its increasingly concentrated exposure to China’s technology sector helped offset weakness elsewhere in the economy.
The trust fell 0.9% on a net asset value (NAV) total-return basis in the six months to July 31, 2026, but outperformed the 5.6% decline in the MSCI China All Shares Index by 4.7 percentage points.
The trust’s share price total return was -3.3%, also ahead of the benchmark by 2.3 percentage points. However, the discount to NAV widened to 9.7%, from 7.4% at January 31, 2026.
Its ongoing charges ratio, calculated at the end of the financial year, remained at 1.06% for the year ending January 31, 2026.
The company reported that its NAV total return had outperformed the benchmark by 18.1 percentage points over the 20-month period from November 29, 2024 to July 31, 2026.
Over the past three years, its NAV total return stood at 30.8% to July 31, 2026, outperforming the benchmark by 11.5 percentage points and recouping a large part of its underperformance since the mandate change.
Following Baillie Gifford’s mandate change in September 2020, through to July 31, 2026, the company’s share price total return and NAV total return underperformed the benchmark by 7.5% and 0.9%, respectively.
The portfolio managers underlined a broader shift in the Chinese equity market, pointing out that the economy remained uneven, with property and domestic consumption weak, while growth was increasingly concentrated in AI, semiconductors, advanced manufacturing and other technology-related industries, where the trust was exposed.
The company’s strongest holdings were ByteDance, Zhongji Innolight, Shandong Sinocera Functional Material, CATL and Weichai Power, while Tencent, Ping An, Zijin Mining, Zijin Gold and Alibaba were among its principal detractors.
The managers said: “Geopolitical uncertainty will remain part of the backdrop, particularly around technology and trade. We therefore continue to focus on the economic consequences for individual companies rather than attempting to predict political outcomes.
“In an increasingly two-speed economy, our focus remains unchanged: to identify exceptional businesses exposed to structural growth, remain disciplined where expectations have run ahead of fundamentals, and use periods of market dispersion to improve the prospective return of the portfolio.”
The trust reported that first-half GDP grew 4.7% year-on-year, with high-tech manufacturing growing by 13.3%, while retail sales increased by only 1.3% and fixed-asset investment fell by 5.7%. The divergence was reflected in the portfolio.
Information technology rose from 11% of assets at the end of January to 16% at the end of July, while communication services remained the largest sector at 26%. Consumer discretionary fell from 25% to 22%.
The trust also has substantial exposure to China’s private technology ecosystem. ByteDance, whose valuation increased by 27%, and RedNote, whose valuation increased by 37%, together represented 16.7% of total assets, compared with 10.4% a year earlier.
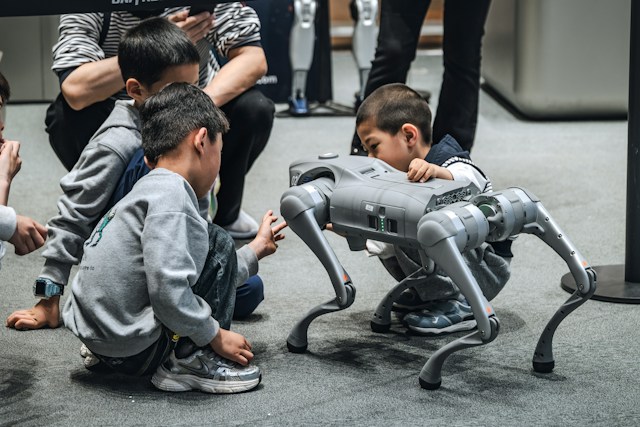
The managers added: “AI and advanced manufacturing should remain important growth drivers. The investment cycle in China still appears relatively early, and the key question is whether current supply constraints begin to ease. We will be watching the ramp in domestic graphics processing units (GPUs), the specialised chips used to train and run AI models, and memory capacity, the pace of cloud capital expenditure and whether AI adoption broadens further into physical applications such as robotics.
“Import substitution should provide an additional multi-year source of demand, while the continued emergence of companies such as CXMT and Unitree reinforces our view that the investable opportunity set is still expanding rather than narrowing.
“The opportunity therefore remains unusually two-sided. In parts of the domestic economy, expectations are sufficiently depressed that stabilisation rather than a full recovery could support attractive returns. Conversely, in areas of technology where valuations have risen sharply, strong operational delivery will increasingly be required to justify expectations. Maintaining discipline on both sides of that divide will remain central to our approach.”
The shares ended July at 306p against a NAV of 338.93p, leaving a 9.7% discount compared with 7.4% at the end of January.
The trust also bought back 2.9m shares, equivalent to around 5% of its share capital excluding treasury shares. Management estimates that these purchases enhanced NAV by around 0.5 percentage points during the period.

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE