Written by:
Bank of England and PRA explore reforms to modernise UK credit union sector and drive growth
 Reading time: 3 minutes
Written by:
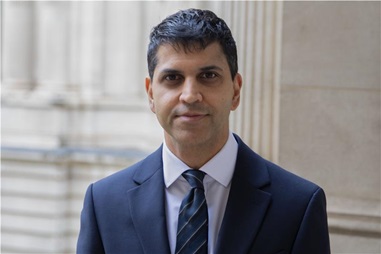
Shoib Khan
The Bank of England and Prudential Regulation Authority (PRA) are exploring reforms to modernise the credit union sector, focusing on driving growth, digital innovation and improving financial outcomes for members.
Credit unions, which are member-owned organisations that typically focus on savings and personal loans within a specific occupation, community or geographical area, have more than two million members across the UK.
Building on the joint PRA and Financial Conduct Authority (FCA) 2025 Mutuals Landscape report, the discussion paper examines whether the regulatory framework remains proportionate as the sector evolves. It also explores how credit unions can expand access to financial services and improve outcomes for their members.
The regulators are seeking views on removing certain requirements for smaller credit unions, including those relating to internal audits and regulatory documents, to cut red tape without compromising financial stability.
Other proposals include creating a risk-based framework for larger, more complex credit unions, giving them greater flexibility over capital requirements, and applying rules used by other smaller deposit takers, such as the standardised approach to risk-weighted assets, in place of the current simple leverage ratio.
The discussion paper will also examine how a simplified version of the Basel framework could be applied to the sector, including streamlining capital add-ons for large credit unions with specific exposures and introducing a simpler capital buffer to help absorb shocks during periods of stress.
The regulators will consider barriers preventing credit unions from offering new products and services, as well as how shared-service providers and third-party organisations could support investment, technology and operational capabilities.
Credit unions will also be given additional guidance on the FCA’s expectations for firms working with third parties to provide important services. The regulators will consider whether changes to FCA fees could reduce regulatory costs and support growth.
Further proposals include giving credit unions a route to convert into building societies, allowing them to benefit from a regulatory framework better suited to their lending activities and a wider range of funding options.
The review will also consider the existing solvent exit framework, exploring whether greater flexibility could be provided to transfer business or restructure in an orderly manner.
The regulators are encouraging credit unions to provide feedback on the options presented and identify any alternative approaches that have not been considered. The proposals are intended to offer greater flexibility to firms with different business models, growth trajectories and risk profiles.
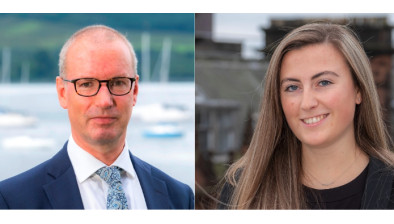
Shoib Khan, director of UK Deposit Takers at the PRA, said: “Credit unions are a vital part of our financial services sector, and we have scope to make their regime even more proportionate and growth-friendly. We want to have an open, transparent dialogue with firms, and I look forward to seeing their honest feedback.”
Sheree Howard, executive director of Authorisations at the FCA, said: “Credit unions provide valuable support to millions of members, including many who may otherwise struggle to access affordable financial services. As the sector evolves, it is important that the regulatory framework keeps pace, enabling credit unions to innovate, grow and meet the changing needs of their members while continuing to deliver good outcomes for consumers.
“We want to hear directly from the sector about what is working well, where barriers remain, and how the regulatory framework may need to adapt to support a strong, sustainable future for credit unions.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE