Written by:
Families favour house deposits over university costs, but IHT could shift thinking
 Reading time: 3 minutes
Written by:
Christine Ross
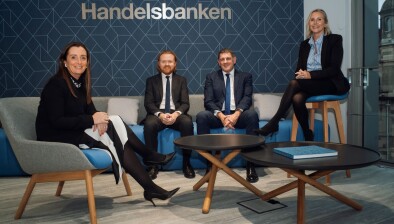
Wealthier families may be missing an opportunity to support younger generations earlier in life, according to new research from Handelsbanken Wealth.
The study suggests a disconnect between how families currently give and how they might use their wealth to benefit the younger generation while taking estate planning into consideration. Experts suggested that reducing the debt of young family members could also offer inheritance tax benefits.
Almost eight in ten (79%) say they have never considered university costs or student debt as part of their long-term inheritance plans. This comes despite the substantial cost of student borrowing, with interest rates on some student loans now reaching 6% in the 2026/27 academic year.
When asked to consider student debt and inheritance tax simultaneously, attitudes shift towards helping with higher education costs. More than four in ten (44%) say they would be more likely to fund university costs or repay student loans if doing so also reduced the value of their estate for inheritance tax purposes.
The research also found that 39% would rather use their wealth to support children or grandchildren during their lifetime than leave them a larger inheritance, while 37% would be more likely to do so if it formed part of an inheritance-tax-efficient financial plan.
It found that 61% believed helping a young person buy their first home would have the biggest impact on their financial future. Just 8% chose helping with higher education costs, including tuition fees, living expenses and student loan repayments.
Meanwhile, around 53% would prioritise a house deposit, compared with 15% who would put the money towards higher education.
Handelsbanken Wealth says the figures reflect what it sees among clients, with house deposits often taking priority.
Christine Ross, head of private office (North) and client director at Handelsbanken Wealth, said: “Helping with a house deposit is often the obvious choice when families want to give younger generations a financial head start, and we see that regularly with clients.
“But university costs can be overlooked. Tuition fees, living costs and student debt can all have a significant impact on a young person’s finances, yet relatively few families appear to consider them as part of wider estate planning.
“The interesting point is that attitudes shift once people understand there may also be an inheritance tax dimension. That does not mean families should make gifts purely for tax reasons, but it does show why education costs deserve to sit alongside property and inheritance when families think about how best to use their wealth.
“The first question should always be whether someone can afford to give money away without compromising their own financial security. Where there is genuinely surplus wealth, looking at the family’s overall position can help determine whether education, property or another form of support is the best use of it.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE