Written by:
IMF praises UK ‘decisive’ deficit action as it warns US and France to get their “house in order”
 Reading time: 3 minutes
Written by:
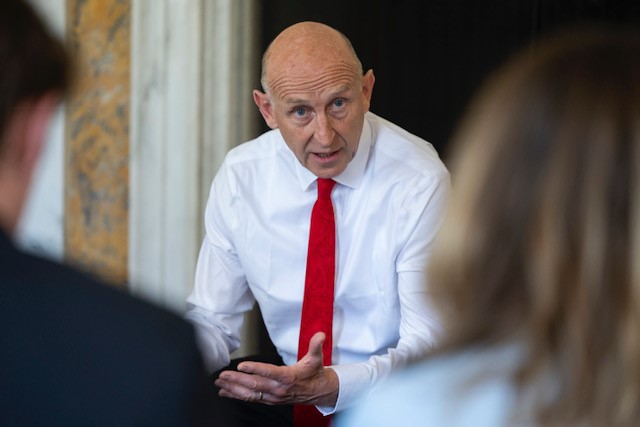
John Healey
The International Monetary Fund (IMF) has praised the UK Government for taking “decisive measures to cut future spending and raise taxes as it urged ministers to “stay the course” ahead of its upcoming Budget.
Kristaline Georgieva, the institution’s managing director, claimed Britain’s budget deficit was on course to fall sharply in the coming years, warning the likes of France and the United States need to follow suit.
She said at the IMF’s annual meeting in Bangkok, Thailand: “The UK is actually one country where action to reduce the deficit has been taken decisively. We see the UK is enjoying a bit better growth prospects [as a result].
“We need to recognise that the UK is not just a systemically important, significant economy, but London is one of the capitals in the world for the finance community. Traditionally we’ve seen more attention, in relative terms in the UK, to what the government is doing. [There is] a bit more sensitivity and I think the government recognises they need to stay the course.”
Chancellor of the Exchequer John Healey is set to arrive this week in Bangkok for his first IMF meeting prior to his inaugural on October 28. Mr Healey said the Government would prioritise “fiscal discipline” despite pressures to raise spending on defence and address the cost of living.
The IMF managing director also hinted at meeting the chancellor and telling him to “reaffirm this confidence in the direction of travel. I do expect that during the annual meetings, there would be an opportunity to convey that message.”
The global financial organisation raised the country’s economic growth prospects by 0.3 percent points to 1.3% this year, one of the biggest upgrades in the G7. It is predicting Britain to record a primary surplus, measuring government tax and spending after paying debt interest of 1.5% of GDP by 2031.
The fund reserved is starkest fiscal warnings for the US, its largest donor country and France was paying the highest premium on its borrowing since 2012 over concerns the government will fail to pass deficit reducing budget this year.
She added: “Get your house in order. Otherwise, your people and our businesses will pay a price. What is our loudest call to policymakers right now? Make urgent repairs to your fiscal house before the cracks widen. Now is the time to enhance revenues to rationalise spending and improve public financial management.”
It noted that the bond sell-off affected most of the developed world economies, adding that some of it “through no fault of their own” are suffering from a rise in their market borrowing costs.
She added: “Markets are granting financing to countries — this is not the problem. The problem is the cost of this financing. It will be heavier and heavier unless the level of debt shrinks. There is no magic. You have to go in a direction of tightening debt, bringing it down and bringing deficits down.”

Share this article:

Subscribe to our newsletter to not miss articles like this one:
 SUBSCRIBE